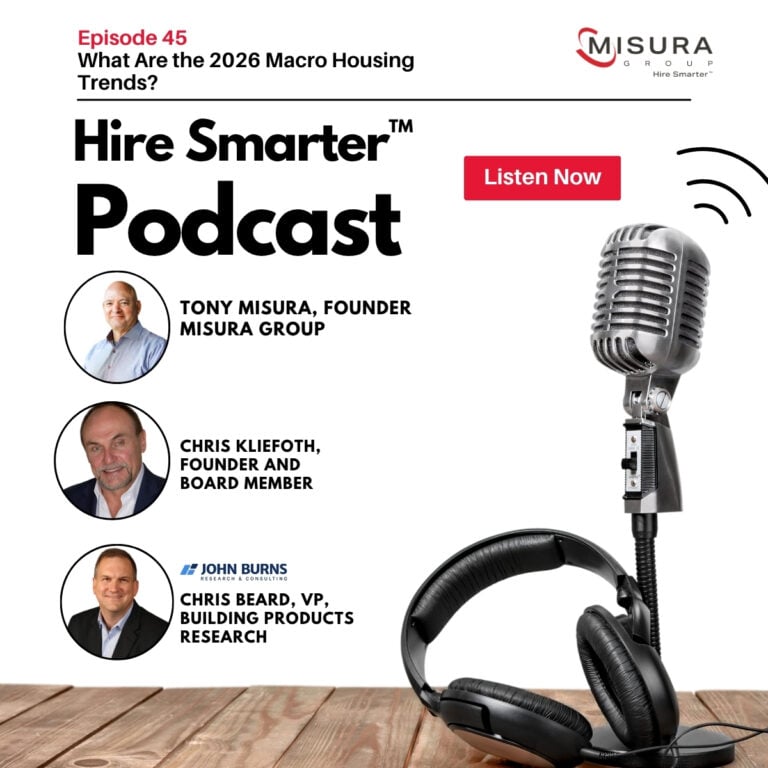
Don’t plan for rate relief. Mortgage rates have stayed above 6% for three years, and neither guest expects them to drop below that anytime soon. Single-family starts are tracking down mid single digits this year, with a flat outlook for 2027.
Long-term new construction demand is shrinking. With first-time buyers now averaging around age 40, boomers aging in place, and immigration slowing, household formations are expected to fall below one million a year. Total starts could settle between roughly 940,000 and 1.1 million starting around 2029 or 2030.
Demand isn’t disappearing. It’s moving. Repair and remodel is already near parity with new construction and is expected to overtake it as the larger share of residential construction.
Remodeling rewards flexibility over scale. Serving remodelers means special orders, flexible inventory, and a different P&L. The upside is significantly higher margins.
Dealers need to get in front of remodelers now. Partner with the large and national remodeling contractors in your market, show up at NARI and local HBA meetings, and use data like home sales, aging housing stock, and storm activity to find demand before it walks in the door.
Chris Beard works on the building products team at John Burns Research and Consulting, which provides research and data that executives across the building products supply chain use to shape their strategic plans.
Chris Kliefoth is the founder of Premier Solutions Group and serves on multiple boards of directors and advisory boards, helping leadership teams plan for what’s next.
If your 2027 budget depends on the market doing the work, this episode is your wake-up call. Watch the full conversation and share it with your leadership team before your next strategic planning session.
Tony Misura: Super excited for our latest episode of Hire Smarter. We’ve got two fantastic guests here. Chris Beard with the John Burns organization, which does research that really every executive leader in the building product supply chain is leveraging to map out and set up their strategic plans as they move forward. And Chris Kliefoth, the founder of Premier Solutions Group, a fantastic fencing business model that continues to grow today. Chris serves on a number of boards of directors and board advisor roles, continuing to help leaders and boardrooms plan for the future. Gentlemen, thank you so much for joining us. I really appreciate it.
Chris Beard: Pleasure to be here. Good to see you.
Tony Misura: As we’ve talked and mapped this out, our first goal here is to give a quick overview of where we see housing starts finishing up for 2026, and maybe some type of peg on what 2027 looks like. All the executives I’m speaking to right now are busy doing their budgets, and with budgets of course comes their forecast and strategic plan. Having two Chrises, I apologize for using last names. Chris Kliefoth, any thoughts on how the year is finishing up?
Chris Kliefoth: Good morning, and I appreciate this opportunity to bounce this subject around. I’ll defer to Chris B for the statistical, data-driven side since he’s the expert in that area. But generally, as we enter 2027, I think we’re looking at a lot of the same in many markets. I don’t think there’s going to be a huge unlock of demand coming from interest rates. And Tony, I have a different view on the interest rate effect on housing than the commonly held macro view. But I think businesses should plan for more of the same and begin to look at their three to five year outlook: who they are, what they want to do, what markets they want to play in. I think now is a bit of a crossroads for some of these organizations. I’m very optimistic about overall demand for construction and construction materials. I just think there’s going to be a lot of shifting of that demand within the pot.
Tony Misura: Chris B, what are your thoughts? How do you see the quarter?
Chris Beard: That’s a great segue, Chris, because we’re in three-plus years of interest rates north of 6%, and planning around interest rates coming down is not in the cards. I think that’s very evident. When there were announcements earlier this year of Fannie and Freddie buying back mortgage-backed securities, I like to joke that for about a minute and a half we got interest rates below 6%. Then the conflict started, and they’ve been north of that since. You look at the trajectory of the 10-year Treasury and some of the actions the administration has tried with bond buybacks to support that, and it’s certainly not in the cards that we’ll see interest rates below 6% anytime soon.
So demand being unlocked because of interest rates probably should not be in your planning scenario. Instead, it’s coping with higher for longer. We’re still in the hangover effect of really low mortgage rates, with people locked into sub-3% rates in some instances. They’re not going to move and take on a new mortgage.
Builders have been creative with rate buydowns, and they’re going to continue to do that. That’s been propping up new construction to an extent. But the new home sales number that came out just yesterday was very disappointing. Builders are sitting on elevated levels of unsold inventory, and they’ve been very open in their earnings calls, saying that until that unsold inventory gets off the books, they’re going to slow their starts. We expect that to carry into 2027. So we’re thinking down mid single digits this year for single family. Our base case is relatively flat for 2027. Then we have some demographic challenges as we move through the outer years, with declining population playing into demand.
Tony Misura: Hang on. Before we go into the future, let’s put a bow tie on the remainder of 2026 and 2027. There are many organizations in the industry that I call sailboat companies. They wait for the tailwinds of the macro to push their profits, their sales, and their share up. What I’m hearing from both of you is there will be no winds. The sailboat’s not going to roll. Is that what I’m hearing?
Chris Kliefoth: In the defined new construction single-family market, and to some degree multifamily, yes, I agree. That doesn’t mean there aren’t tailwind opportunities in the industry.
Tony Misura: Great distinction. But from a straight-up housing start perspective, new construction single family and multifamily, where are we on total starts, Chris B? Around 1.3 million?
Chris Beard: Roughly, on total starts, yeah.
Tony Misura: So if you’re going to throw a peg on 2027, are you going to say 1.1 million, or do we drop below 1 million? What do you think?
Chris Beard: For total starts, no, we’re not going to be that low. Multifamily is still going to be a bigger part of the picture. And like I said, we’re thinking roughly flat single family in 2027.
Tony Misura: Perfect. So whatever the outcomes were for 2026, we’re going to rinse and repeat for 2027. If any organization out there is not happy with their share gains or where their sales are, it’s up to them to do something different, because the macro environment is not going to help them or change significantly in those segments.
Now let’s take a shot at a much larger challenge: the overall new construction market, or, as Chris K is forcing us to do, segmenting it out. But first let’s identify the problem, meaning the demand destruction around new construction, single family and multifamily, in the five to ten years to come. Who wants to take the first swing at that?
Chris Beard: At John Burns, we have a great demographics team that looks at age cohorts and where people are in the cycle. There’s been a lot of chatter in the industry, and I know the Joint Center did some work on it a couple of years ago looking at population growth. We’re really going to be in low-growth mode for household formations over the next ten years.
The good thing is, if somebody’s 40 today, we know ten years ago they were 30, and ten years from now they’re likely going to be 50. So we can see the age of the population and where people are in the cycle. We’re seeing a big jump in the 75-plus group. Boomers are retiring, lifespans are longer with improvements in healthcare, so they’re staying in their homes longer. Then we have the wave of millennials coming in. What’s interesting is the first-time homebuyer is now roughly 40. That’s a big shift. Traditionally, you bought your first home in your late 20s, generally a starter home, then you had kids and moved into your move-up home in your 40s or early 50s. Seeing that first-time buyer at age 40 changes the landscape pretty significantly.
Then you take into account the changes from immigration. There have been significant policy changes over the past couple of years with this administration, and that’s expected to continue, and depending on how 2028 goes, it will impact demand too. Immigration is a significant demand driver, primarily in the for-rent space, so apartments and rental homes. But it’s still taking demand out of the picture. So looking at long-term growth from population to household formation, it’s going to be relatively low and way below historical norms.
Tony Misura: The historical norms have been 1.3, 1.4 million for the past fifty years or more, right?
Chris Beard: In household formations, around 1.2 million a year. We’re expecting household formations to dip below a million each year because of the demographic changes we’re seeing.
Tony Misura: Is there a bottom? Go ahead, Chris K.
Chris Kliefoth: I agree with Chris B’s conclusions. He comes at it from a flow: household formations in, retirees out, and how that flows through the age and housing demographics. I come at it from more of a marketing approach, but reach exactly the same conclusion. Today there are roughly 150 million residences in the United States, and as time goes on, we’re not going to need many more than that. The total addressable market, the total housing stock, is not going to need to grow dramatically. That doesn’t mean there aren’t huge opportunities within that pie, but the pie’s not going to grow. In fact, I believe the pie will probably stop growing as soon as 2028 or 2029, given the vagaries of the market with interest rates and things like that. As population begins to go negative, absent immigration changes, around 2030, people leave their houses and go into alternate housing at some point. So the conclusion is the same, coming at it from a different analysis.
Chris Beard: That’s a great point, Chris K. I talked about the huge population growth in 65-plus and 75-plus. People are staying in their homes longer. I think the initial assumption was that we’d have this huge wave of existing homes hitting the market as retirees sell and move on. We’re not really expecting that, with advancements in technology and aging in place. One lesson learned in COVID is that maybe it’s not good for mom and dad to move into a big multifamily retirement community. These homes are paid off, so they’re not worried about making a monthly mortgage payment on a fixed income. So we’re not anticipating a huge wave of existing homes hitting the market, certainly not in this rate environment. I think there are opportunities in the R&R space for boomers aging in place, and household formations are still coming. So you’re right, the total pie isn’t necessarily growing, but there are still opportunities because there’s still demand for housing.
Tony Misura: Let’s define that new construction pie. On average it’s been about 1.3 million starts in the seventy-five years since World War II. What do you see for demand destruction and step down? Five to ten percent a year?
Chris Kliefoth: No, that would be tremendously disruptive. I think you’re talking about half a percent to one percent per year for total housing units.
Tony Misura: So the pie is going to shrink half a percent to one percent per year. Do we have a bottom? Any thoughts on where that would level out?
Chris Beard: In the 2030s, I’d say about 1.1 million, maybe.
Tony Misura: You and I have been having this conversation since Harvard put out their report eighteen months or two years ago, saying something like 500,000 starts would become the new normal after 2035. Is that right?
Chris Beard: I don’t know the exact number off the top of my head.
Tony Misura: At that point, your analysis was that they weren’t calculating the extended lifespans.
Chris Beard: Life expectancy.
Tony Misura: Life expectancy from medical advances. Is that still where your data lands?
Chris Beard: I think so. It’s also really hard to predict the immigration piece. We do expect some unlocking there, not as significant as we’ve seen in past years, but that demand will likely come back too. So there is a floor. And it changes by geography. I’ve used this example before: a boomer finally moves out of homeownership in Maine. That doesn’t do a University of Georgia graduate in Atlanta any good, because they don’t want to live there. The Sunbelt is going to continue to be a growth area, and that’s still going to need housing. I think the Midwest is probably a growth area too. You can’t just look at the total national number and say this is what it’s going to be, because it’s going to vary by region.
Chris Kliefoth: Correct. Internal migration will drive demand for new construction but be neutral to demand for overall housing stock, which is what Chris B was referring to: shifting within geographies. That’s one of the micro markets within the macro market. But builders are pretty in tune with that. They’re going where the people are going today. So I don’t know that it’s a major new opportunity for the top 15 builders and the supply chain into them. They’ve already repositioned themselves to take advantage of internal migration.
Tony Misura: It’s interesting on the dealer side too. Dealers over $300 or $400 million in revenue are also migrating with their acquisitions, following their customers in that direction. The real concern is dealers that are more geographically constricted. They operate in a smaller micro market, and these effects will have a more dramatic impact on their business model. It’s another dot to put up in the boardroom as they map out their strategic plan. Chris K, Chris Beard said 1.1 million for a floor. Is your floor relatively close?
Chris Kliefoth: It’s really quite close. I ended up with a range of 940,000 to 1.05 million in my calculations. Maybe I’m a hair more pessimistic on immigration.
Tony Misura: Got it. So this is significant. Chris is talking about a thirty percent drop.
Chris Kliefoth: By the way, that begins in 2029 or 2030, not next year.
Tony Misura: Got it. So we’ve got five to eight years to prepare for this, or for the slow incremental elements of it. Either way, Chris B is saying a twenty percent reduction and Chris K is saying a thirty percent reduction on the standard baseline of new construction starts, single family and multifamily. Is that a pretty close thumbnail? So the next question, which I know you both want to jump into, is where are the opportunities? Where should businesses be looking at other industry segments or sub-segments where these dollars are going to flow, or where the need is going to be for building materials?
Chris Beard: Before we pivot into that, one thing inherent in this discussion is that with low population growth, but not complete demand destruction, we’ve been looking at job growth, which is reflected in recent BLS data. Declining population also means a smaller workforce. We had job declines last month, and growth was anemic the month before. Earlier in the year it was stronger. But the wave of retirees is going to continue. What I’ve been hearing from dealers, from builders, from manufacturers, from every industry segment, is that labor is a challenge. That’s why you can see anemic job growth while the unemployment rate ticks down. These are people leaving the workforce or no longer looking. We think stock market gains this year played into that to an extent. So we can have pretty anemic job growth numbers and still a tight labor supply. That’s a big factor too. Chris K, interested in your thoughts on the other growth opportunities, but that tight labor supply is going to continue.
Tony Misura: And certainly the current administration’s immigration policy doesn’t help that.
Chris Kliefoth: The job growth number cuts both sides of the supply and demand equation. If there is demand, it’s harder for the industry to create supply. And as people leave the job market and the total job market shrinks, that creates less demand. So you’re getting hurt both ways. But again, the repositioning opportunity is huge. Massive.
Tony Misura: Tell us about that. What do you see?
Chris Kliefoth: I come at it two ways. First, I look at the total pie as having six drivers of demand, most of which we’ve touched on: immigration; replacement of destroyed housing, around 250,000 units a year; the luxury market, where people want the newest, latest, best things; bringing some of the underhoused into the market; the second home market, which is a fairly small segment; and the teardown and rebuild element. I look at those six sub-segments of the current pie as opportunities for people to reposition themselves within the existing pie.
But the bigger opportunity may be to change your TAM, your total addressable market, and redefine it to include R&R. There’s been this historic Berlin Wall between new construction and remodeling, with the exception of smaller regional or local builders that may do some of both. The top 15 builders are on the new construction side and ignore R&R. If you think back to when you and I both had hair, Tony, the big thing for the large national and regional builders was consolidating demand in a highly fractured market. That’s how they got to be what they are today. I think the same playbook could be applied to the R&R market, which is even more fractured and somewhat non-professionalized. That’s a way for them to redefine their TAM and start implementing growth strategies that can replace some of that future demand destruction.
Chris Beard: If you look at the share of total residential construction, it’s almost parity now between R&R and new construction, and we expect R&R to take over, due to the factors we’ve discussed: fewer housing starts, aging housing stock, people staying in their homes longer. And near term, the mortgage rate lock-in effect. People are staying in a home that may be too big or doesn’t meet their needs, because that sub-4% interest rate is really hard to give up. That’s a near-term driver. But R&R is certainly the bigger opportunity in total residential construction.
Tony Misura: The fragmentation of R&R still fascinates me. One of our clients is a $600 million business, and a significant portion of it is a high-end custom entrance door systems business that anchors their millwork side. We placed the president there, and in learning about the business, I asked about their top 10 customers. I’ve been doing this for 27 years, and I’d heard of only one of their top 10 customers. The fragmentation in door and window replacement on the R&R side is amazing. And it’s a giant market, larger than the new construction market by their calculations.
Chris Kliefoth: I agree with Chris. Right now it’s an awfully close parity market, around $450 billion each, give or take $50 billion one way or the other in a given year. I agree with the premise, and you can point to this model being pursued by various groups within specific product categories. You have home remodeling companies going national or multi-regional in bathroom remodels and window replacements, a little bit in roofing, and other categories. They’re building significant companies in one or two product categories. But that places the burden on the homeowner to essentially design and GC their own long-term remodel. I think there’s an opportunity to bundle more into a remodeling project, especially with the aging housing stock, where you do gut jobs or major remodels to bring that housing stock back into the active market.
Chris Beard: And there’s a lot less visibility, which is what Chris K is implying. With new construction, there’s developed land, a builder has a community, and you can plan around that. They’ll tell you their pace of starts. You can look at new home sales. There’s a lot more visibility. So from a dealer’s perspective, it’s more predictable. You can’t predict a homeowner thinking, “I need to do this someday.” You don’t know until that homeowner raises their hand and contacts a contractor or walks into a showroom. My wife and I did a major deck remodel this summer. Nobody was planning around that. I bought the materials at a local lumberyard, and nobody knew about it until I walked into the showroom and said, “We’re going to do this.” So it’s more difficult to predict, and demand generation has to come more from the contractor side, putting these ideas into the homeowner’s mind. I agree with Chris, there’s a bigger opportunity in major remodeling projects, and we’re already seeing that. It’s going to trickle down from the luxury segment, which has been propping things up the past couple of years, into the mid-size jobs. But there has to be demand generation to do that, because there’s not a lot of visibility and you don’t know when a homeowner is ready until they’re ready.
Chris Kliefoth: And what you just expressed doesn’t make the demand any less real. It just makes it more fractured and unpredictable. Isn’t that an opportunity for somebody to come in and generate predictability, demand consolidation, and purchasing efficiencies, and bring the marketing these large builders have been so great at? Every one of them has a brand name, and that brand name is transferable.
Tony Misura: For those large production builders, doesn’t the profit predominantly come from developing land? Isn’t that where the majority of their net profit comes from, with building the home being a necessary evil to optimize their position on the property? Is that right?
Chris Beard: I can’t dive into the builders’ P&Ls specifically. Certainly the land piece matters, and developed land costs are still elevated. But you’re right about the brand name. A Pulte home is different from a Toll Brothers home, which is different from a Lennar home. They have a stronger brand position there. And there’s still the predictability piece. Here’s the community, here’s the development, people drive by and say, “Let me look at that.” On the R&R side, you just don’t have that visibility.
Chris Kliefoth: Tony, the flip side to the land argument might be that the margin opportunity on remodeling work is a bit higher than on new construction. I don’t believe the average local remodeler is optimizing economies of scale in crew planning and deployment. There are opportunities there. Yes, it will be a different-looking P&L. Your sales cost will look different, your material margin will look different. But those may be the adjustments needed to get access to a larger TAM.
Tony Misura: Does installed sales then become a core strategic position for dealers, providing a much easier, one-stop solution to the renovation and remodel problem?
Chris Beard: To an extent it can. But if your core customer becomes the remodeling contractor instead of the home builder, that looks different. A remodeling contractor isn’t going to say, “I’m fine being the GC, dealer, you come put the windows in.” The contractor is going to say, “I’ve got my crew. I want to do that.”
Tony Misura: Interesting. So subcontractors would feel more pressure from that install offering. If it’s not install, then what? From an R&R perspective, SKU proliferation and the inventory dynamic are more challenging. Is that something to be solved at the dealer level, at the two-step distribution level, or some combination of both?
Chris Beard: On the R&R side, you have more flexibility on cost, so margins are typically higher. It’s messy, like we said. It’s very disjointed and not as consolidated. But you move more into special order. Think about your stock positions. With new construction, you stock a bunch of 3050 windows and make sure you have enough when the builder says, “I’m ready for these.” On the R&R side, it’s more special order. The contractor sells something, and then you get into lead time issues. The homeowner has more input into the product going into the home they’re already going to live in. They want something a little nicer, or they want to trade down, which we’re also seeing with affordability. But it’s not necessarily a stocked product. The homeowner needs 17 different sizes to fit their openings, and then it becomes about lead times and supplying the product without it stretching three months or longer into the future. You may keep standard decking in stock, but when the homeowner wants something different, it takes longer. That’s why I say it’s messier, but the margins are generally significantly higher.
Tony Misura: You’ve both said demand prediction is more difficult, combined with the fragmentation of the marketplace. How do you solve that problem?
Chris Beard: Get involved in local organizations and talk to the big contractors. We all know who the big contractors are in our respective markets. I know who they are here in Des Moines, Tony knows, Chris knows. Build those relationships and figure out what their pipeline looks like. There are opportunities for partnership on lead gen and understanding that pipeline. So it’s not just a contractor walking in the door saying, “Here’s a big job I’m doing over the next month that wasn’t on your radar.” Joint business planning helps too.
At John Burns, we do research on where those hot pockets are. There are remodeling contractors that respond to hail or storm damage, and that’s predictable to an extent. The Midwest had hail damage, so we know these neighborhoods will need new roofs. That’s low-hanging fruit. You see a storm, and you know there’s going to be a bump in R&R in the next couple to six months. You can also look at household incomes and aging housing stock. Where are the homes built twenty or thirty years ago, in the early 2000s boom before the GFC? Those homes probably still have their original windows and roof. Some of the larger remodeling contractors are getting very sophisticated at micro-targeting at the neighborhood or community level. You look at home transactions, because when somebody buys a home, there’s usually more major R&R within about six months. So there is some predictability. You can figure out where these hot pockets are within the various metros.
Chris Kliefoth: Tony, I assume that question was from the perspective of the dealer and supplier network, not the end remodeling contractor. I would hope the trend is for remodeling contractors to get larger, more professional, more organized, with a broader scope, and to defragment the demand the supply chain supplies into. I agree with Chris B that it’s harder work, but it’s not totally unpredictable, especially in concentrated remodeling markets. Rural markets get a little more haphazard. But in the major metro and suburban markets where housing rehab is happening, it’s predictable. Home sales predict it. Teardowns are predictable, and they’re actually a long-cycle event. Gut jobs, where they leave a facade and redo the whole unit, are long-term projects with milestones like demo permits that let you predict demand. Yes, the work will be harder for the supply channel, but it can be lucrative. And it may be necessary.
Tony Misura: Then you’ve got the James Hardie approach, where they target all the homeowners in an area with homes that are 20, 30, 40 years old, hit them with coupon discounts on their product line, consolidate those leads, then walk into a market like Indianapolis and say, “We’ve got 10,000 remodels that need to be done. Installer, you get to bid on this work. Dealer, you get to bid on distributing it, and it’s going to be a single-digit margin because we captured the sale.” This is a more fragmented space. And I love subcontractors, we need more of them in the industry, but their strengths generally aren’t sales and marketing. For dealers to rely on these fragmented customers to do that marketing reach is a big ask from my perspective. Is there a way dealers can copy that Hardie approach?
Chris Beard: I don’t necessarily agree that subcontractors aren’t sophisticated in sales and marketing. Some are very sophisticated in their targeting approach, and that leads to some predictability. There’s a channel we identified a few years ago that we call mega contractors. These are national contractors with branch locations in the major metros where they think it’s strategic to be active, and they have really robust lead pipelines. So I do think there are some that dealers can partner with that do a good job managing their leads and pipeline, with outside sales forces, sometimes literally canvassing neighborhoods or sending direct mail, but generating leads. In my experience working with a lot of dealers, they’re not necessarily partnering with these organizations, and that’s a big opportunity. There’s also the National Association of the Remodeling Industry. Go to their meetings, raise your hand, and say, “Here I am. Let me be your supplier.” There are great opportunities there to uncover leads and get more predictability into the pipeline.
Tony Misura: Clearly, the data I have on R&R is a gap, and I need to read the John Burns reports more closely. Pick a market, like your Des Moines market. How many large, well-organized renovation and remodel contractors will you have? Five? Ten?
Chris Beard: There are at least a dozen that are reputable, and even more when you get into specialties. Some are really good at roofs. Some are design-build firms that are really good at whole-home remodels. We haven’t even talked about the interior design community and the architects sketching this stuff out. There are opportunities there. Every market has them. There are national players too, like Power Home Remodeling. They’re a national brand with local branches, they specialize in exteriors like siding, roofing, and windows, and they’re very sophisticated. Go to your local HBA or local home show and you’ll find them.
Tony Misura: Are they buying direct, or relying on local supply chains?
Chris Beard: In some instances they buy direct, but primarily they go to the traditional pro dealers, the traditional LBM dealers. And look at what the big box stores have been doing the past couple of years. Home Depot and Lowe’s are targeting the pro and investing a lot of money and resources into that audience. That’s not necessarily the home builder. Would they turn away home builder business? Absolutely not. But they don’t have lumberyards. So they’re going after the sophisticated pro remodeler with a marketing organization, a sales organization, lead gen, and forecasting. That’s where there’s opportunity for the independents to capture some of that audience. They probably already have a fair amount of that business, but they need to make it a focus.
Chris Kliefoth: I think that’s right, Chris. Look at Home Depot’s narrative on their last quarterly call. They’re clearly recognizing this trend and positioning themselves to be a great supplier to the larger pro remodeling contractors in specialty trades and products, instead of waiting for them to walk in the door after a home transaction, which has been the traditional model. And Tony, I think you might be underestimating how well connected some of these dealers already are that have focused on this market. The dealer market bifurcates into new construction versus repair and remodel. The good ones cross over both. But there’s still a fair amount of segmentation, and some dealers are very in tune with their local remodeling companies. And the business models Chris mentioned, the LeafFilters and Bath Fitters of the world, are working in specific product categories, and I think that will continue to grow.
Chris Beard: I agree.
Tony Misura: One example: Spahn & Rose in the Atlanta market opened up a decks-only supply business. They have thirty-four subcontractors waiting with their trailers every morning when they open the gate to load up and roll. With the fragmentation and SKU breadth around decks and railings, specializing and being a category killer in that space has been a fantastic, really successful model. Chris K, as people sit in the boardroom and plan out their strategy going forward, any recommendations for them?
Chris Kliefoth: It depends on which boardroom you’re sitting in. A builder’s boardroom? A two-step wholesaler’s boardroom? A specialty vertically integrated contractor’s boardroom? The answer would vary.
Tony Misura: Let’s say dealers and distributors specifically.
Chris Kliefoth: It’s a very simple thing. Figure out how to get engaged with the remodeling industry in your local market and become the go-to location for those contractors. It’s a simple theme, and I don’t think it’s terribly new. But if you’ve traditionally depended on tract building and new home construction for the majority of your business, your demand isn’t being destroyed. It’s being changed and moved. But you have to move with it.
Tony Misura: Yes, it’s not new, it just becomes much more important for organizations to lean in this direction. It just flashed in my head walking through a yard with one of our client presidents, pointing to twenty-five semi trucks that get rolling at five in the morning to get two first outs within twenty miles. From a renovation and remodel perspective, those large semi trucks might not be the best fleet to have if you’re not dumping a whole lot.
Chris Beard: And that’s an advantage for the local independents. They know their market better than the national chains. They know the intricacies of local code, product selection, where the neighborhoods are. That’s a strength for local dealers: literally knowing the people doing the work, what’s important to homeowners, and what will and won’t fly. That local focus will enable them to succeed more than a national chain coming in with a one-size-fits-all approach.
Chris Kliefoth: Tony, I think the premium will be placed on dealers for flexibility versus scale and efficiency, because of the demands of a remodeling market relative to a new construction market. That yard you walked through was all about scale and efficiency in servicing the builder. To be relevant to a remodeling contractor, you need flexibility: inventory flexibility, product flexibility, because it’s not going to be standardized.
Tony Misura: That’s a profound statement. Wow, what a theme.
Chris Beard: And the upside is the margins. The margins are higher because of that.
Tony Misura: If you can get your sales team trained to move off that 24% gross margin block. Man, I learned a lot today. This is really excellent. Chris B, tell me about John Burns Research and Consulting. Do you have research specifically directed at the R&R space? How are you pivoting your organization to serve this?
Chris Beard: We do. As a firm, we focus on a lot of new construction. We work with most of the home builders and understand that supply chain, land developers, build-to-rent operators, and apartment developers. But I sit on the building products team, and R&R is a major focus area for us. I just created a graphic depicting R&R as 80% noise and 20% hard data. It’s a murky picture, and I understand the trepidation dealers may have about getting into the space, because the data isn’t clean. Like I said, you don’t know when somebody is ready to do a whole-home remodel until it happens.
But we do a lot of in-depth research into specific geographies and markets to identify where the opportunities are, like the swaths of homes that are twenty years old and ripe for remodel. We also look at cycle times. Using roofing as an example, it doesn’t matter how old the home is. It matters how old the roof is. So you have to look at permit data and when things were replaced. It’s difficult because you may not have fifty homes ready at the same time. You may have one here, one over there, one over here. It’s harder to target. But a lot of our focus is figuring out where those areas are. Our demographics team looks at household demographics, like where the more affluent homeowners are. Target affluent homeowners in older homes. It sounds as obvious as the sun rising in the east tomorrow, but it’s not that simple, and you can identify where those pockets are. The national mega remodelers have become really sophisticated at doing that. I get a direct mail piece once a week from somebody wanting to do something on my home. It was built in ’94, and I’ve made significant renovations myself, as did the previous owners. But they understand this is a neighborhood with bigger, older homes, so they target it.
We have quarterly surveys focused on the kitchen and bath industry and on the whole-home remodeling industry. We talk with residential architects and the design-build community about opportunities, identifying trends and geographies. We work with these large firms, they tell us where their opportunities are, and that’s a great asset for dealers. It’s also a great asset for manufacturers to see the demand coming down the pipeline and plan around it.
Decking is a good example. It continues to be the category that’s outperforming, because outdoor living is still number one and has been growing since COVID. A couple of years ago, I was talking to dealers who thought decking would start to decline. Absolutely no way. There’s ongoing share shift from pressure-treated lumber to composite decking. You hear AZEK, which is now part of James Hardie, and Trex talk about one to two percent conversion per year, sometimes a little more. These categories are still growing. There’s great opportunity, and we can help dealers and manufacturers uncover where those pockets are.
Tony Misura: Gentlemen, this is fantastic. Thank you so much. I really appreciate it. For those who haven’t already, please include John Burns Research and Consulting in your data collection and research as you map out your strategic plans. Every conversation is a jewel of knowledge. Again, thank you so much, gentlemen.
Chris Beard: Pleasure, thank you.
Chris Kliefoth: Thank you, Tony. Thanks, Chris.